Bank of Canada Holds at 2.25% Again — Seventh Straight Pause as Tariff and Oil Risks Rise
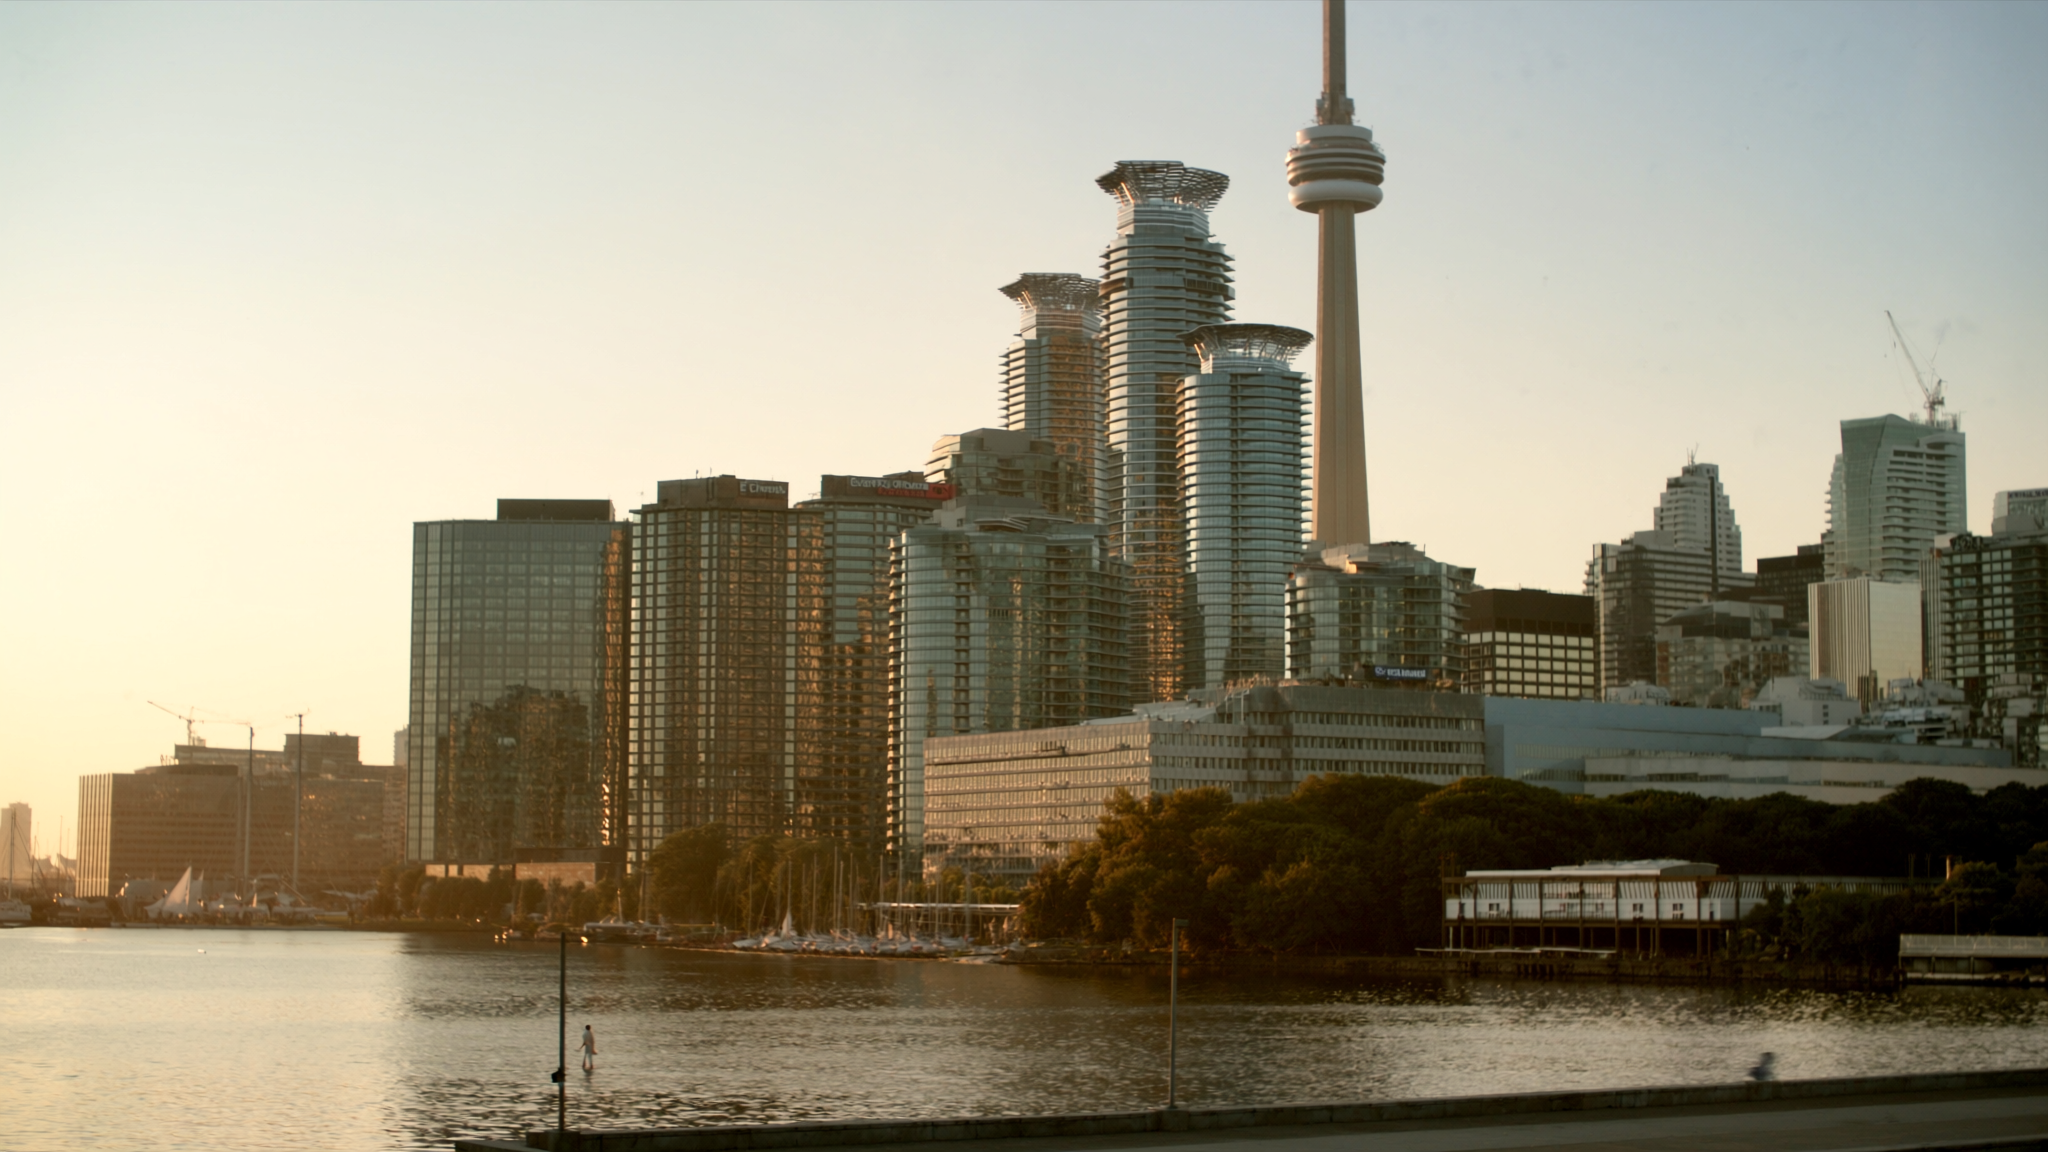
On September 2 the Bank of Canada left the overnight rate at 2.25% for a seventh straight decision. Growth and inflation tracked the July forecast, but Governing Council flagged higher upside inflation risks from oil and new Canada–US tariffs — the key read for Ontario mortgage holders heading into fall.
The Bank of Canada held its target for the overnight rate at 2.25% on September 2, 2026, leaving the Bank Rate at 2.5% and the deposit rate at 2.20%. That is a seventh consecutive decision without a move — the policy rate has sat at 2.25% since the late-October 2025 cut. For Ontario homeowners on a variable-rate mortgage or a home-equity line, nothing about this announcement changes your contractual rate today.
What changed is the risk mix underneath the hold. Governing Council said the economy and inflation have evolved broadly as forecast in the July Monetary Policy Report, so the rate stayed put. At the same time, the Bank said upside risks to inflation have increased, while new tariffs make growth prospects more uncertain. That is the line mortgage planners and GTA buyers should actually read twice.
The decision in one glance
- Overnight rate: held at 2.25% (Bank Rate 2.5%, deposit rate 2.20%)
- Streak: seventh straight hold at 2.25% (no change since October 2025)
- Next scheduled announcement: October 28, 2026 (next Monetary Policy Report the same day)
Growth rebounded. Housing was part of it.
Canadian GDP rose 3.3% in the second quarter after a very weak first quarter, the Bank said. Some of that strength was temporary, but the pick-up was broad-based: consumption rose, exports and business investment jumped, and — after several weak quarters — there was some rebound in housing activity.
Labour market conditions also improved: the unemployment rate edged down to 6.4% in July. Demand for labour remains subdued, and the Bank still sees excess supply in the economy. Put together, Governing Council reaffirmed a broadening recovery — then immediately flagged that new US tariffs and threats of further action pose risks to how durable that recovery is.
Inflation is still about gasoline — so far
CPI inflation has been hovering around 3% in recent months, mainly because of persistently higher gasoline prices. Excluding gasoline, inflation was 2.2% in July, and measures of core inflation remained close to 2%. So far, the Bank says there has been little evidence of higher energy prices spreading into other components.
That containment is not a free pass. With the Middle East conflict ongoing and little progress reopening the Strait of Hormuz, the Bank says upside risks to its inflation forecast have increased. The longer high oil prices and elevated refinery margins persist, the greater the risk of spillover into other goods and services. New US tariffs and Canadian counter-tariffs will also raise costs for some businesses and could feed into consumer prices over time.
Financial conditions tightened since July
Long-term bond yields have moved up globally, including in Canada, since July. The Canadian dollar has appreciated slightly on US-dollar weakness. For anyone locked into a variable rate or approaching a renewal, that bond-yield move matters more than the unchanged overnight target: renewal pricing tracks the curve, not just the overnight print.
What this means for Ontario buyers and homeowners
If you are buying: the Bank is not cutting into the fall listing season. Payment math that assumed a September cut should be rebuilt around 2.25% holding at least through the October 28 decision. The Bank’s own read still includes a rebound in housing activity in Q2 — useful context next to soft GTA resale volumes earlier in the summer — but tariff and oil risks cut both ways on affordability.
If you are renewing or carrying a variable rate: your Bank of Canada-linked rate does not move on this decision. Watch the bond market and lender posted/discount spreads into October, not just the overnight headline. Governing Council said it is prepared to adjust policy as needed; it did not signal an imminent cut.
If you are selling or advising clients: lead with the risk paragraph, not the hold itself. A seventh pause at 2.25% was widely expected. The new information is higher upside inflation risk from energy and tariffs alongside more uncertain growth — a setup that keeps the Bank on the sidelines rather than easing into the fall market.
Sources
- Bank of Canada, Bank of Canada maintains the policy rate at 2¼%, Fixed Announcement Date press release, September 2, 2026.
- Bank of Canada, Monetary Policy Decision Press Conference Opening Statement, September 2, 2026.
Written by
Frank Lee
Market news and data explainers
Market news and data explainers. Writes from public releases (TRREB, CMHC, StatCan, BoC) with original analysis for Ontario / GTA readers.
View all articles by Frank →