This Week in GTA Real Estate: Tariff Rent Pressure, Bulk Condo Buys, and Softer Asking Prices
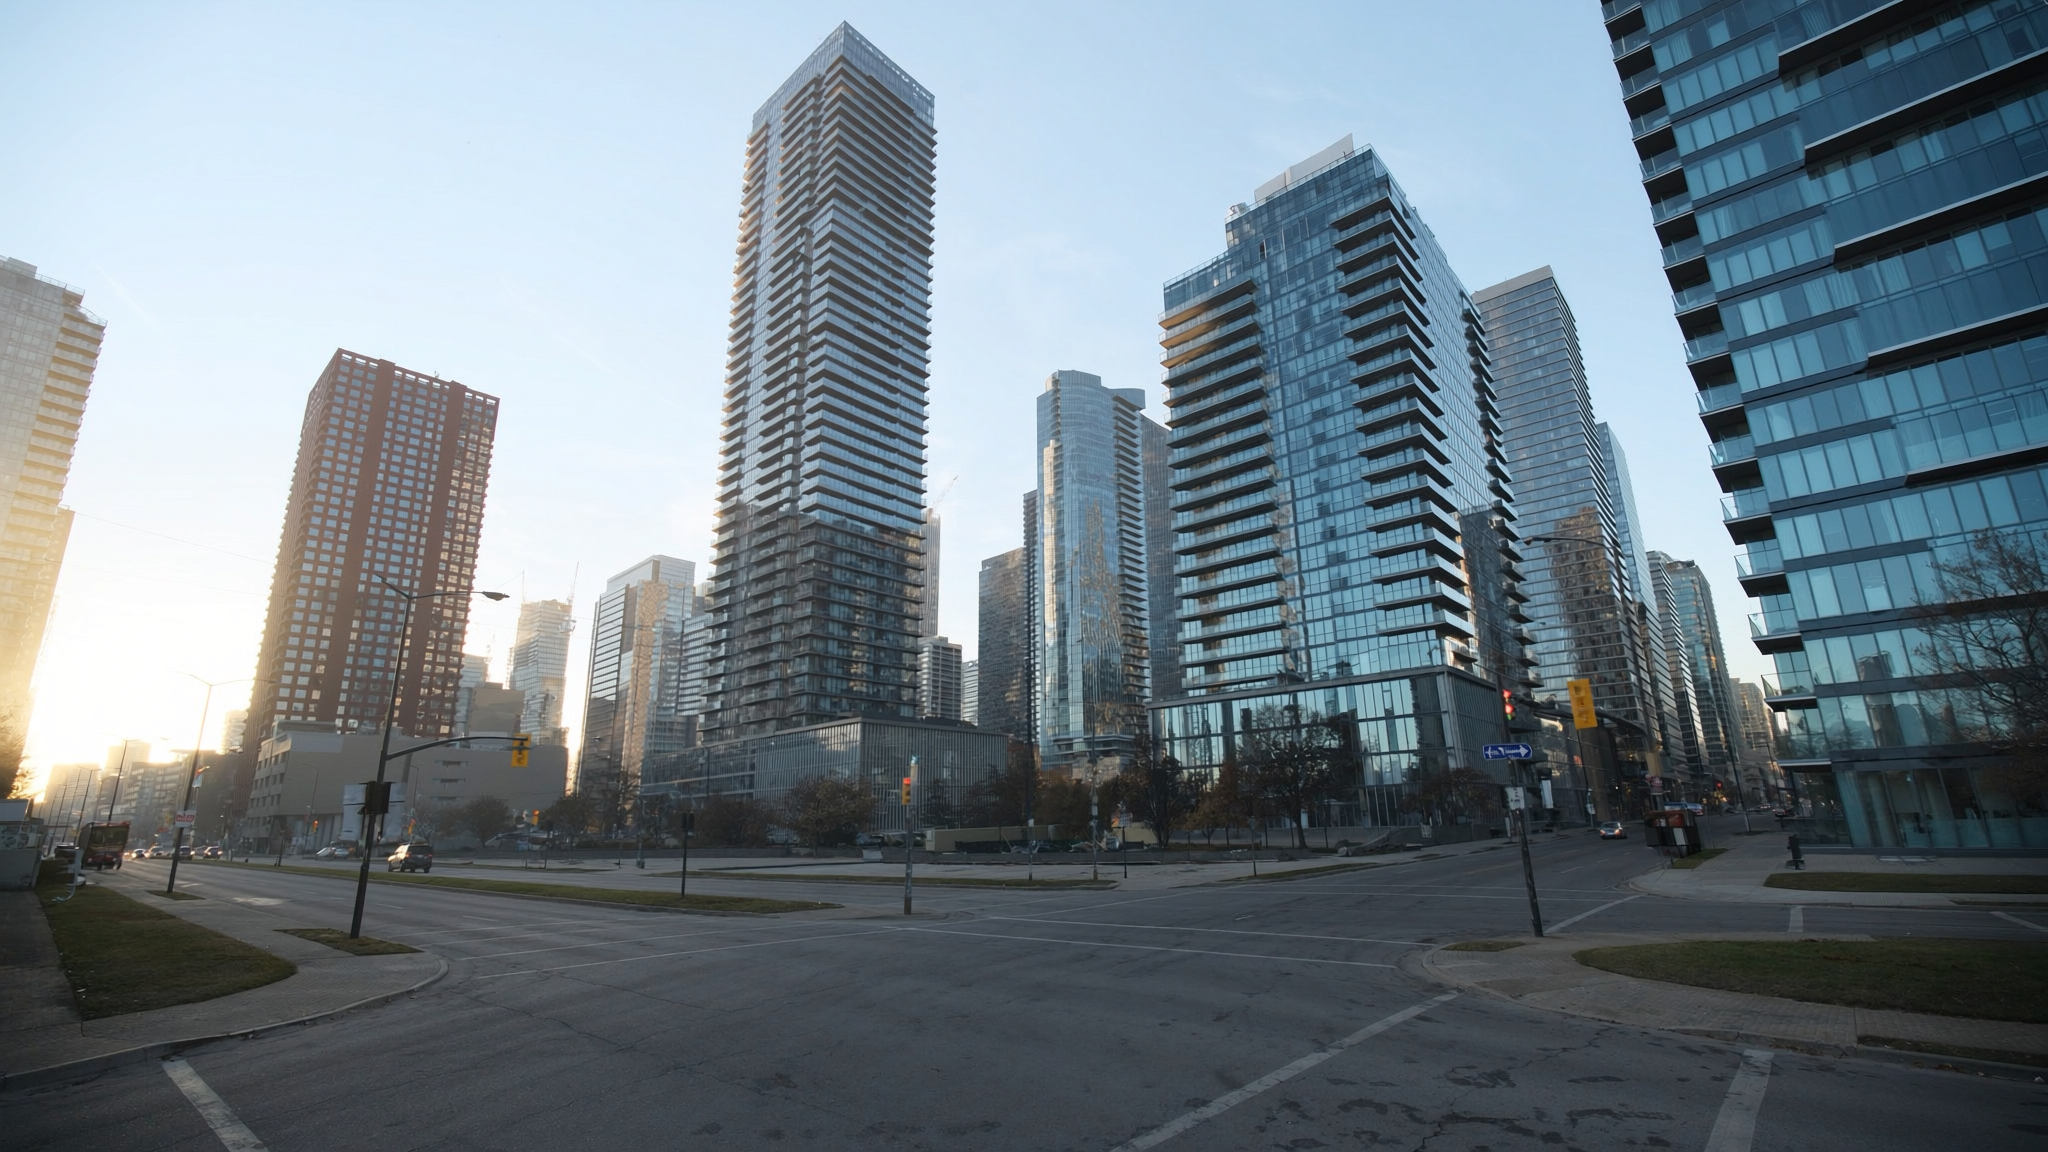
Urbanation flagged tariff pressure on Toronto rents, Ontario-backed capital bulk-bought midtown condos, BILD's low-rise rebound held, and nearly four in five August GTA sales closed under asking. Here is the week's notable reporting — and where we land.
This week the primary tape was already on the record: Rentals.ca and Urbanation's September 22 tariff analysis, StatCan's 2024 Canadian Housing Survey affordability jump we covered earlier, and July building-investment figures that showed Ontario hospitals leading while multi-unit spending slipped. By Friday the street debate had shifted to what tariff exposure, unsold condo inventory, and soft asking-price outcomes mean for a fall GTA open. Here is the week's notable reporting, and where we land.
1. Rentals.ca / Urbanation: tariffs as the next rental pressure
Rentals.ca and Urbanation, in their September 22 press note, argue tariffs will shape Canada's rental market before they fully show up in asking rents, with Toronto and Vancouver most exposed on the high-rise supply side and tariff-exposed cities already seeing faster rent declines on the demand side.
Our take: we already published the Market News read of this release. The Ontario angle that still matters is the pipeline lag: purpose-built rental now carries most new construction, so steel-cost pressure and shelved 2026 starts become missing completions later in the decade — right when population growth is expected to rebound. Treat softer near-term asking rents and a thinner future completion calendar as the same story on different clocks.
2. The Globe and Mail: High Art Capital's first bulk condo buy
Rachelle Younglai, in The Globe and Mail on September 22 (updated September 23), reports Ontario-backed High Art Capital paid $22.3 million for 43 unsold units at the Line 5 midtown towers — about $518,000 a unit on average — as the $1.3-billion fund's first publicized transaction, with a plan to convert inventory into rentals including below-market units for SEIU health-care members.
Our take: this is the cleanest street-level proof that unsold Toronto condo stock is being absorbed off the retail price list. Bulk discounts and rental conversion ease some completion overhang for developers, but they also reset comps for nearby retail buyers and keep investor IRR assumptions tied to rent spreads, not flip premiums. Watch how many more of these deals surface before year-end.
3. BILD / Altus: low-rise HST rebound, high-rise still lagging
BILD, citing Altus Group on September 22, reports 907 GTA new-home sales in August — well above last year's record-low August but still 37% under the 10-year average — with 692 single-family sales running 47% above the 10-year average while condo/stacked sales of 215 remained about 78% below their long-run August norm.
Our take: the temporary HST rebate is doing real work on ground-oriented product; high-rise is still the bottleneck. That split matters for land, labour, and absorption forecasts into 2027: treat "new-home recovery" as a low-rise headline until condo eligibility and construction timing catch up.
4. REMI Network / HouseSigma: four in five August GTA sales under asking
REMI Network, drawing on HouseSigma data published September 24, reports 79.3% of August GTA sales closed below the seller's final ask, with a median discount of about 3% (~$24,000) and Ajax/Markham among the more competitive municipalities while Caledon, Halton Hills, and Oakville sat near the top of below-ask share.
Our take: put this next to TRREB's August Market Watch we already covered (sales −2.1% y/y; new listings −14.1% y/y; average price under $1M). Fewer listings and widespread under-ask outcomes can coexist: sellers who do list are still conceding, while municipalities with tighter competition (Ajax, Markham) are not a GTA-wide "buyer's free-for-all." Pricing strategy is local, not regional.
5. Wealth Professional / UBS: Toronto bubble risk eases to moderate
Steve Randall, for Wealth Professional on September 25, summarizes UBS's 2026 Global Real Estate Bubble Index: Toronto and Vancouver have moved from high to moderate bubble-risk territory after roughly 10% real house-price declines over the past year, while affordability remains tight and higher-for-longer financing costs are expected to cap near-term gains.
Our take: a lower bubble-risk label is not an affordability green light. For GTA buyers and agents, the useful pair is "correction acknowledged" plus "ownership costs still elevated versus incomes." That keeps rental demand sticky even as resale and pre-construction pricing reset.
Further reading
Primary releases we covered this week: Urbanation / Rentals.ca tariff rental analysis, StatCan 2024 CHS affordability, and July building investment. Figures above are drawn from those releases or from the linked reporting — we do not invent numbers.
Sources
- Rentals.ca / Urbanation, Rentals.ca press, September 22, 2026.
- Rachelle Younglai, The Globe and Mail, September 22, 2026.
- Building Industry and Land Development Association (Altus Group), GlobeNewswire, September 22, 2026.
- REMI Network / HouseSigma, REMI Network, September 24, 2026.
- Steve Randall, Wealth Professional (UBS Global Real Estate Bubble Index 2026), September 25, 2026.
Compiled by the Real Estate HQ editorial desk. Figures cited from primary sources are reported as of their release date. Linked articles are the work of their respective authors and publications; commentary is our own.
Written by
Frank Lee
Market news and data explainers
Market news and data explainers. Writes from public releases (TRREB, CMHC, StatCan, BoC) with original analysis for Ontario / GTA readers.
View all articles by Frank →